Every day, countless people swipe their cards or tap their phones, driven by emotion more than a plan. What if saving could be as effortless as spending? The journey from reactive, impulsive spending to deliberate, repeatable saving isn’t about tougher willpower—it’s about designing systems that make saving your default choice.
Imagine Sarah, who once found herself plagued by buyer’s remorse after every shopping spree. She didn’t lack desire to save—she lacked a structure that made saving nonnegotiable. By flipping her environment and routines, Sarah transformed her finances, turning an unreliable impulse into a steady, empowering habit.
At its core, saving competes with the allure of immediate gratification. A shiny gadget at checkout or a late-night online deal delivers instant pleasure, while the benefits of a funded emergency fund remain distant. Without intervention, spending will always win.
Moreover, many of us treat saving as what’s left over after bills and bills of wants are paid, rather than carving it out first. Relying solely on self-control is like expecting to swim upstream without assistance; it works sometimes, but it exhausts you quickly.
Research shows that financial self-control strategies had an average effect size of 0.57 in improving saving behavior. Yet building structural supports—rather than leaning on motivation alone—yields the most consistent results.
Savvy savers shift three levers: environment, automation, and goals. When these factors align, saving becomes almost effortless.
Moving from chaotic spending to strategic saving is possible with a structured, step-by-step approach. Here’s how to get started today:
True habit formation hinges on repetition and celebration of small wins. Starting with a modest, attainable contribution sets you up for success. When you consistently save the amount you can handle—say $25 per paycheck or $1 a day—you cultivate an identity as someone who saves, not just spends.
Visual reminders, like marking a calendar each time you automate a transfer, reinforce the practice. Over time, what felt like a forced action becomes an automatic part of your monthly routine. This is the essence of tiny, consistent daily contributions.
An accountability partner or coach can heighten commitment. Sharing milestones with a friend, spouse, or community amplifies the reward and anchors your new saving identity in a social context.
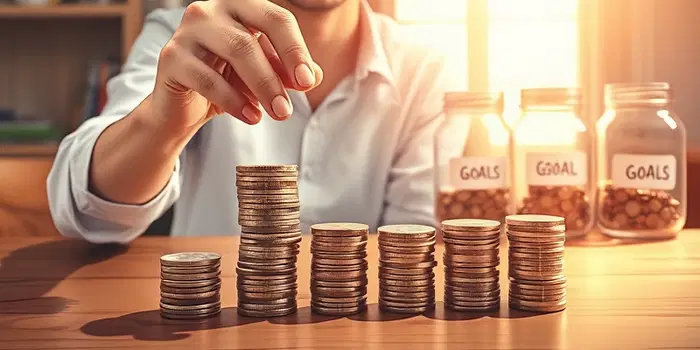
Frameworks like the 50/30/20 rule simplify allocation: half your income for necessities, 30% for wants, and 20% for savings or debt repayment. Treat savings as a non-negotiable expense line—never the leftover choice.
If you currently save 2% of your income (the median in one Federal Reserve survey), aim to raise that to 5% within six months, then toward 20% over a few years. Even modest increments compound into meaningful balances.
Saving isn’t a finish line; it’s a way of life shaped by systems, routines, and environment design rather than occasional bursts of willpower. By separating your money, automating contributions, defining clear goals, and introducing friction against impulse purchases, you turn saving into a default action.
Your first step could be as simple as setting up a $1 daily transfer. From there, each automated deposit, each small celebration, and each monthly review reinforces your identity as someone who saves intentionally. Over time, you’ll look back and realize that what began as a tiny habit transformed your entire financial story.
References