Insurance is more than a policy; it’s a pivotal part of a robust asset-protection strategy. By entering into a contractual arrangement for risk sharing, individuals and businesses can safeguard savings, property, and income. From unforeseen medical expenses to major liability claims, thoughtful insurance planning ensures that a single event does not dismantle years of hard-earned wealth.
Whether you’re a homeowner, a professional, a parent or an entrepreneur, understanding the breadth of available coverages and making informed decisions can bring financial protection against specified risks and lasting peace of mind. This guide explores the primary types of insurance, outlines decision factors and offers a clear process for choosing the right policies.
Often described as the first line of defense, liability insurance covers damages or injuries you cause to others. It is essential for anyone who could face a lawsuit due to property damage, bodily harm, or personal injury claims.
Key examples include personal liability in homeowners policies, auto liability for vehicle accidents, general liability for businesses, and professional liability or malpractice policies. These protect against legal fees, settlements and judgments, ensuring that one incident does not force you to liquidate assets.
Property insurance safeguards your own assets—homes, commercial buildings, equipment and personal belongings—against loss or damage. Standard homeowners policies typically encompass four main areas: dwelling protection, personal property protection, liability coverage and living expenses if you must relocate temporarily.
It’s vital to review policy exclusions carefully. For example, flood damage often requires a separate policy, while earthquakes may need additional riders. Aligning coverage with your region’s specific hazards will help you avoid unexpected gaps.
Auto insurance is central to protecting both your vehicle and your financial wellbeing. In addition to covering liability for accidents, most policies offer collision coverage, comprehensive protection against theft or vandalism, and weather-related damage.
Because premiums and coverage options vary widely, shoppers should compare quotes from multiple carriers. Checking insurer licensing status and complaint records can reveal service quality, while bundling auto insurance with other policies often unlocks discounts.
Homeowners insurance combines property and liability protection under one umbrella, covering repairs to your home and replacement of personal belongings. If a fire or storm renders your house uninhabitable, additional living expenses may be reimbursed.
Renters insurance, though less expensive, offers critical coverage for tenants: it replaces personal property, covers liability for injuries in your unit and, in some cases, pays for temporary housing. For renters, this policy often provides the highest risk-to-cost benefit.
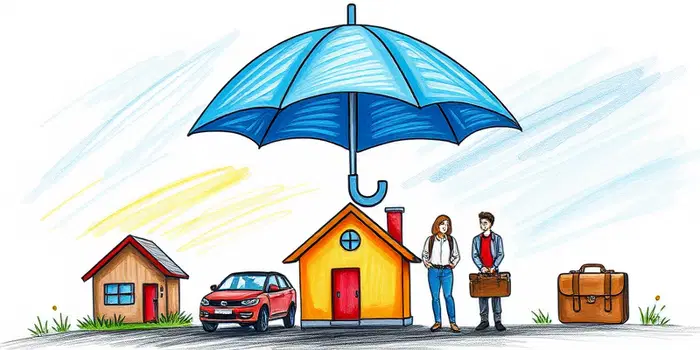
Umbrella insurance provides extra liability coverage beyond limits in standard policies. When a claim exceeds your auto or homeowners liability limits, an umbrella policy absorbs the excess, preventing the depletion of your savings.
Because umbrella insurance is relatively affordable, it can be a cost-effective safeguard for families, business owners and anyone with valuable assets, rental properties, or heightened exposure to lawsuits.
Medical expenses can quickly escalate into overwhelming debt or asset liquidation. Quality health insurance shields you from this risk with a combination of premium, deductible and out-of-pocket maximums.
When selecting a health plan, evaluate provider networks, drug formularies and potential subsidies. Balance the trade-off between lower premiums and higher deductibles against your expected medical needs and budget to find optimal coverage.
Considered by many experts to protect your most valuable asset: your ability to earn an income, disability insurance replaces a portion of your salary if illness or injury prevents you from working. By maintaining a stable cash flow, this coverage prevents forced withdrawals from retirement accounts or emergency savings.
Life insurance ensures financial stability for your dependents after your passing. The two primary forms are term life, which provides coverage for a set period, and permanent life, which includes a cash-value component for long-term wealth preservation.
Term life is ideal for temporary obligations, such as mortgages or education costs, while permanent policies can support estate-planning goals and serve as an internal liquidity tool.
Service professionals—doctors, lawyers, accountants and consultants—face unique legal risks that standard liability policies may not cover. Malpractice insurance or professional liability policies fill this gap, defending against claims of negligence or errors in judgment.
Business owners often rely on a Business Owner Policy (BOP), combining property, general liability and business interruption coverage. Additional specialized products include workers’ compensation, employment practices liability insurance (EPLI) and key person insurance to preserve continuity in the event of a critical employee’s departure.
Beyond core coverages, consider:
Choosing the right insurance involves comparing cost versus coverage value and matching policies to your risk profile. Key factors include:
By following these steps, you can build a tailored insurance portfolio that protects your home, vehicles, family, income and business against unexpected financial shocks. Remember, no single policy can cover every risk, but a thoughtful combination can create a formidable safety net.
Insurance is an investment in resilience. With the right policies, you can face life’s uncertainties confidently, knowing your assets and loved ones are shielded. Start today by assessing your needs, comparing options and securing the coverage that aligns with your long-term goals.
References