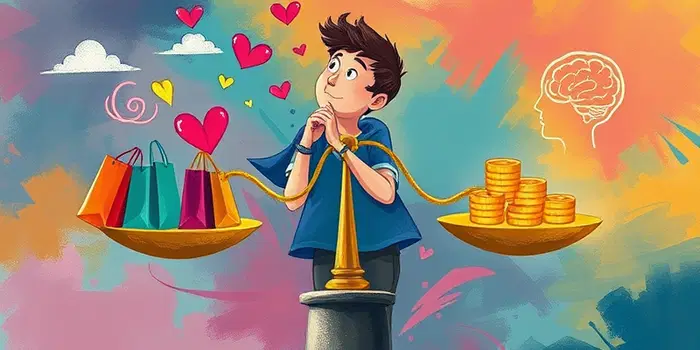
In our modern world, spending is often framed as a simple choice between need and want. But beneath the surface lies a complex interplay of psychology, emotion, and learned behavior. Understanding these forces empowers us to reclaim control over our finances, align spending with our values, and build lasting financial well-being.
Every time we purchase something that sparks joy—be it a warm cup of coffee or the latest gadget—our brain releases dopamine, a neurotransmitter associated with pleasure and reward. This shopping triggers dopamine release response can make buying feel irresistible, priming us for repeat behavior.
Emotional spending is often an emotional spending as a coping mechanism, activated by stress, sadness, boredom, or excitement. While the immediate lift can feel gratifying, it rarely addresses the underlying emotion and can strain finances over time.
The theory of the “pain of paying” explains why the method of payment shapes our perception of cost. When we part with physical cash, the loss feels immediate and tangible. Credit cards, on the other hand, delay that sting, making it easier to overspend without remorse.
By choosing more tangible payment options, you can increase awareness of each transaction and reduce impulse purchases.
Our earliest experiences with money—whether through parents’ spending habits, family discussions, or childhood allowances—lay the foundation for our adult financial behaviors. These “money scripts” often operate below conscious awareness, guiding how we handle scarcity, risk, or abundance.
For example, growing up witnessing frequent financial stress can instill a scarcity mindset vs abundance mindset, leading to hoarding behaviors or fear-based decisions. Recognizing these inherited patterns is the first step to rewriting your money narrative.
Decades of research confirm that interventions targeting money scripts can shift behaviors. By journaling beliefs and challenging negative self-talk—like “I’m bad with money”—you can build new narratives that support financial flourishing.
Beyond emotions, subtle biases skew our financial choices. Limited-time offers tap into the scarcity effect, anchoring influences make us perceive a “deal” based on an arbitrary reference point, and FOMO drives purchases to avoid regret. These mental shortcuts often override deliberate evaluation.
By shining light on these distortions, we can pause before acting and cultivate more rational spending habits.
Mastery begins with mindful awareness and deliberate habit changes. Below are proven strategies to strengthen self-control and realign spending with long-term goals.
Mental budgeting, where you assign psychological labels to money—like “fun fund” or “rainy day savings”—helps mental budgeting and self-control, reducing the likelihood of impulse purchases.
True mastery of your money mindset extends beyond budget adjustments. It requires an ongoing commitment to align every financial decision with your core values and life goals. This process deepens self-understanding and fosters a sense of purpose in your financial journey.
Cultivating an abundance mindset centered on growth encourages proactive planning, investment in personal development, and generosity—toward yourself and others. Over time, you transform money from a source of stress into a tool that supports your vision for a meaningful life.
By continuously reflecting on your motives, tracking progress, and celebrating small victories, you break free from reactive patterns and embrace a deliberate path to financial freedom.
Final Thoughts: Spending is more than arithmetic. It is an expression of our emotions, upbringing, and beliefs. By understanding the psychological forces behind each purchase and adopting targeted strategies, you can reshape your money mindset, reduce impulsive spending, and build lasting financial well-being.
References