In a world obsessed with speed and instant results, the art of waiting patiently can feel countercultural. Yet, when it comes to personal finance, cultivating the ability to resist immediate pleasure in favor of larger gains later is nothing short of revolutionary. By mastering the skill of delayed gratification, you unlock the very mechanism that transforms modest contributions into lasting wealth and shields you from the perils of impulsive spending.
Delayed gratification refers to the choice to forgo a smaller, immediate reward in anticipation of a larger, more valuable payoff down the road. In the realm of money management, this often looks like saving rather than splurging, investing instead of frittering away cash, or applying extra funds to reduce debt rather than upgrading your lifestyle prematurely.
At its core, this practice relies on behavioral basis for saving, investing and underscores the intimate link between your financial habits and your long-term well-being. The ability to pause before spending is not simply about moral strength—it is a deliberate strategy to give your money time to work for you.
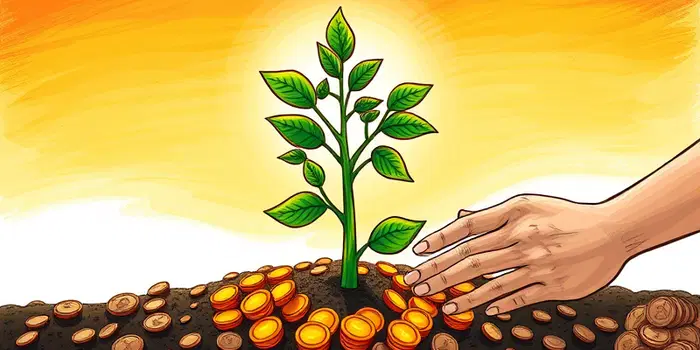
The true power of waiting lies in the phenomenon known as compounding, often hailed as the magic ingredient in wealth building. Compounding means that the returns you earn on your investments begin to generate their own returns, creating an exponential growth pattern over time.
Imagine you invest $1,000 today at an annual 7% return. Ten years later, that initial principal nearly doubles. Two decades out, it almost quadruples. Thirty years on, it soars to more than seven times its original value. By choosing to let your funds remain invested rather than tapping into them for a quick thrill, you harness the relentless momentum of compound interest.
Psychologists and economists have devoted decades to understanding why some individuals easily defer pleasure while others are driven by the lure of the present moment. Studies show that those who score high on delay-of-gratification measures tend to exhibit stronger self-regulation, reduced impulsivity, and a pronounced future orientation.
Despite the celebrated marshmallow test of the 1960s, recent findings caution against overstating a single childhood exercise. Rather, it appears that broader self-regulation across life stages offers a more reliable predictor of financial success.
Beyond academic studies, patient individuals demonstrate consistent habits that steadily build their financial resilience. Their approach is characterized by intentional decisions and smart defaults that reduce the temptation to stray from their plans.
Patience is not an inherent trait reserved for the naturally disciplined. It is a muscle you can strengthen daily. By deploying simple, repeatable tactics, anyone can shift from impulsive spending to conscious wealth-building.
Navigating the path to lasting wealth is less about grand gestures and more about the small, consistent choices we make every day. By resisting the urge to spend impulsively and allowing your resources to compound, you lay the groundwork for a future of security and abundance.
Patience in finance is not passive inaction—it is a deliberate decision to trust in time, harness the mechanisms of compound growth, and fortify yourself against momentary temptations. Embrace this powerful mindset, and you will discover that sometimes, the most potent action you can take is simply to wait.
References